How Do You Create a Balance Sheet in Excel?
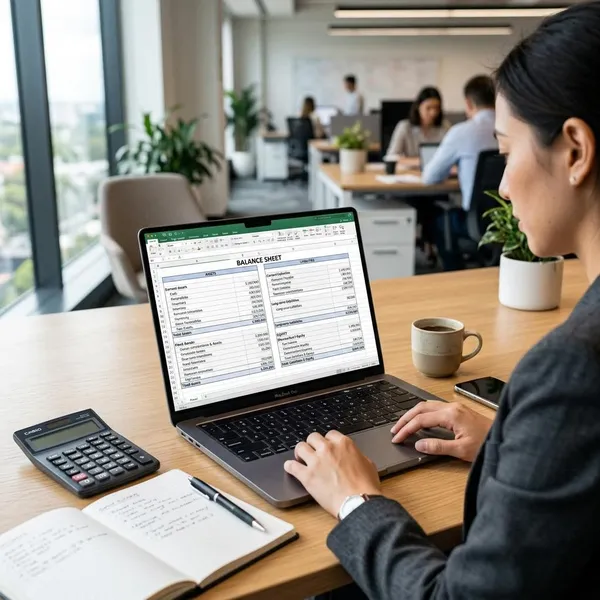
A clear balance sheet format in Excel should organize assets, liabilities, and equity so that total assets equal total liabilities plus equity. Create separate sections for current and noncurrent assets, current and long-term liabilities, and shareholders' or owner's equity, then use formulas to calculate each subtotal and the grand totals. Add a visible balance check, such as "Balanced" or "Needs Review," to confirm that the accounting equation works before sharing or using the spreadsheet.
What a balance sheet format in Excel includes
A useful Excel balance sheet needs a reporting date, clear account sections, amount columns, subtotals, final totals, and one check line that proves the sheet balances. If you only list accounts without that final check, the file may look tidy but still contain a serious mistake.
Assets liabilities and equity sections
The three main sections are assets, liabilities, and equity. Assets show what the business owns, liabilities show what it owes, and equity shows the remaining owner value after obligations are considered.
- Assets: cash, bank balances, receivables, inventory, equipment, vehicles, or other resources.
- Liabilities: supplier bills, credit card balances, taxes payable, loans, or other obligations.
- Equity: owner's capital, retained earnings, current year earnings, or shareholder equity.
Account details and reporting dates
A balance sheet is prepared as of one specific date, not for a date range. Put the business name, statement title, and reporting date at the top so anyone opening the file knows exactly what the numbers represent.
Account names should stay consistent from period to period. If you call an account Accounts Receivable in January, avoid renaming it Customer Balances in February unless you have a good reason. Consistent labels make comparison easier and reduce classification mistakes.
Totals and balance checks
Each section should have its own subtotal, and the worksheet should end with total assets, total liabilities, total equity, total liabilities and equity, and a balance check. The most useful check is simple:
If the result is zero, the sheet balances. If it is not zero, check for missing rows, incorrect signs, and formula ranges that skip a cell. In everyday Excel files, skipped cells are often the problem, especially after someone inserts a new account line.
Create a balance sheet format in Excel
The safest way to build the sheet is to create the structure before entering numbers. That prevents a common mistake: typing figures wherever there is space and trying to make the layout look like a statement afterward.
Use one column for account names and one for amounts. If the sheet will be reused every month, add a date cell at the top and avoid typing the same date into multiple places.
Set up the main sections
Create the title area first, then add the major sections in this order: assets, liabilities, and equity. Within assets, put current assets before long-term assets. Within liabilities, put short-term obligations before long-term debt.
A simple structure works well for a freelancer who only tracks cash, receivables, a laptop, and a few bills. A retail business with inventory, equipment, sales tax payable, and loans needs more categories because the owner has to see what is liquid and what is tied up in stock or fixed assets.
Add accounts and financial values
Enter each account under the section where it belongs. The quick test is practical: if it is something the business owns or can use, it is usually an asset; if it must be paid, it is usually a liability; if it represents the owner's remaining stake, it belongs in equity.
| Account | Where it usually belongs | Check before entering |
|---|---|---|
| Cash in bank | Current assets | Use the balance as of the reporting date. |
| Customer invoices not yet paid | Current assets | Include only amounts still collectible. |
| Supplier bills | Current liabilities | Do not forget bills received but not yet paid. |
| Business loan | Current or long-term liabilities | Separate the portion due soon if needed. |
| Owner investment | Equity | Keep it separate from business income. |
Be careful with negative numbers. Accumulated depreciation, owner draws, or losses may need different treatment depending on how your accounts are kept. If the file is for tax, lending, or formal reporting, it is worth having an accountant review the setup.
Add formulas for totals
Use SUM formulas for each group instead of typing totals manually. For example, if current assets are in cells B6 through B10, the subtotal can be =SUM(B6:B10).
- Subtotal current assets before moving to long-term assets.
- Subtotal current liabilities before long-term liabilities.
- Total assets should combine current and non-current assets.
- Total liabilities and equity should combine liabilities plus equity.
After adding formulas, test the sheet by changing one account value. The related subtotal and final balance check should update automatically. If they do not, the formula range is probably wrong.
Check that assets equal liabilities and equity
The final check should be visible near the bottom of the sheet, not hidden on another tab. A zero result means the accounting equation balances; a non-zero result means the report should not be used yet.
When the check fails, review in this order: formula ranges, missing accounts, wrong signs, then classification. That order saves time because Excel formula errors are usually faster to find than accounting classification issues.
Structure a balance sheet template in Excel
A template should be easy to reuse without breaking formulas. The goal is to make the editable cells obvious and keep subtotal and check formulas protected from accidental changes.
If you prepare a balance sheet once for a loan application, a clean one-date layout may be enough. If you update it every month, build the template so you can add accounts later without rewriting the whole file.
Organize assets by category
Put current assets first because they are the amounts most likely to affect short-term cash decisions. Cash, receivables, inventory, and prepaid expenses usually belong here.
Long-term assets can follow in a separate group. Equipment, furniture, vehicles, and accumulated depreciation are easier to understand when they stay together instead of being scattered through the sheet.
This split matters in real use. A business can look strong because it owns expensive equipment but still struggle to pay bills if cash and receivables are low. Separating asset categories makes that risk easier to see.
Separate liabilities and equity sections
Keep liabilities and equity separate even though they are added together for the balance check. They answer different questions: liabilities show outside obligations, while equity shows the owner's claim after those obligations.
- Current liabilities: bills, taxes payable, credit cards, and short-term loan amounts.
- Long-term liabilities: loans or obligations not due in the near term.
- Equity: owner capital, retained earnings, current year profit, or similar accounts.
If you are using the sheet for your own review, this separation helps you see whether growth is coming from retained value or from taking on more debt. For a lender or partner, it also makes the report easier to read.
Format totals and key financial lines
Use formatting to protect the logic of the sheet, not just to make it look nicer. Bold section totals, add borders above final totals, and use a different fill color for input cells if other people will enter numbers.
Freeze the top rows if the account list is long, and consider protecting formula cells once the template works. A small setup like that can prevent a monthly update from turning into a formula repair job.
Balance sheet example for Excel
A short example makes the format easier to copy into Excel. The numbers below use a small business with cash, receivables, inventory, equipment, payables, a short-term loan, and owner equity.
Use the example as a layout model, not as a rule for which accounts every business must have. A service freelancer may not need inventory, while a shop or small warehouse usually does.
Simple format for small businesses
A small business can start with one amount column and a single reporting date. That keeps the first version manageable and lowers the chance of broken formulas.
Once the sheet is working, you can add a comparison column for last month or last year. Add that only when you will actually use it; extra columns make a spreadsheet harder to maintain if they are only there for appearance.
Example asset and liability entries
Here is a sample set of entries as of December 31, 2026:
| Section | Line item | Amount |
|---|---|---|
| Current assets | Cash | $8,500 |
| Current assets | Accounts receivable | $3,200 |
| Current assets | Inventory | $2,000 |
| Non-current assets | Equipment | $6,000 |
| Non-current assets | Less accumulated depreciation | ($1,000) |
| Current liabilities | Accounts payable | $2,400 |
| Current liabilities | Credit card payable | $1,100 |
| Current liabilities | Short-term loan | $2,000 |
| Equity | Owner's capital | $10,000 |
| Equity | Current year earnings | $3,200 |
The important detail is not the exact account list. It is the placement. Cash and receivables should not be mixed with payables, and owner capital should not be treated like income for the period.
Example totals and balance layout
Using the example amounts, total assets are $18,700. Total liabilities are $5,500, and total equity is $13,200. Liabilities plus equity also equal $18,700, so the balance check returns zero.
| Excel line | Amount | Formula idea |
|---|---|---|
| Total current assets | $13,700 | Cash + receivables + inventory |
| Total non-current assets | $5,000 | Equipment less accumulated depreciation |
| Total assets | $18,700 | Current assets + non-current assets |
| Total liabilities | $5,500 | Payables + credit card + loan |
| Total equity | $13,200 | Owner's capital + current year earnings |
| Balance check | $0 | Total assets - liabilities and equity |
A zero balance check does not prove every account is classified perfectly, but it does tell you the equation works. If the report will be used for taxes, financing, or investor discussions, the next step is to review the account classifications, not just the math.
Conclusion
A good Excel balance sheet should let you check the big picture quickly: what the business owns, what it owes, and whether the remaining equity makes sense. Start with a simple structure, keep formulas visible, and do not trust the file until the balance check is zero and the accounts are in the right sections.